
Welcome to the Schmoozeletter Blog. Your source for weekly water cooler wisecracks from the world of finance. If you have an opinion different than mine or a topic you want to hear about, let me know!
This week, we’re talking about:
Who gets the Premium?
Lots of companies reported quarterly earnings this week!
Some Mr. Market rewarded and some Mr. Market beat over the head with a rubber hose.
Some stock prices are way down at a discount. Some are trading up at a premium.
Let’s play the newest Schmoozeletter game and see…
Who gets the premium?
As our baseline for “Who gets the premium?” we will use the average S&P 500 company. The forward price-to-earnings for the average is currently around 20. This means the average company’s price is about twenty times what they are expected to make in earnings per share over the next twelve months.
So if a company’s forward earnings are more than twenty, they are at a:
Premium!
So if a company’s forward earnings are less than or equal to twenty, they are at a:
Discount!
Ready to play?!
Let’s do it.
GE – General Electric aka GE Aerospace
Everyone’s favorite microwave-turned-aerospace company.
They beat on their quarterly earnings estimates.
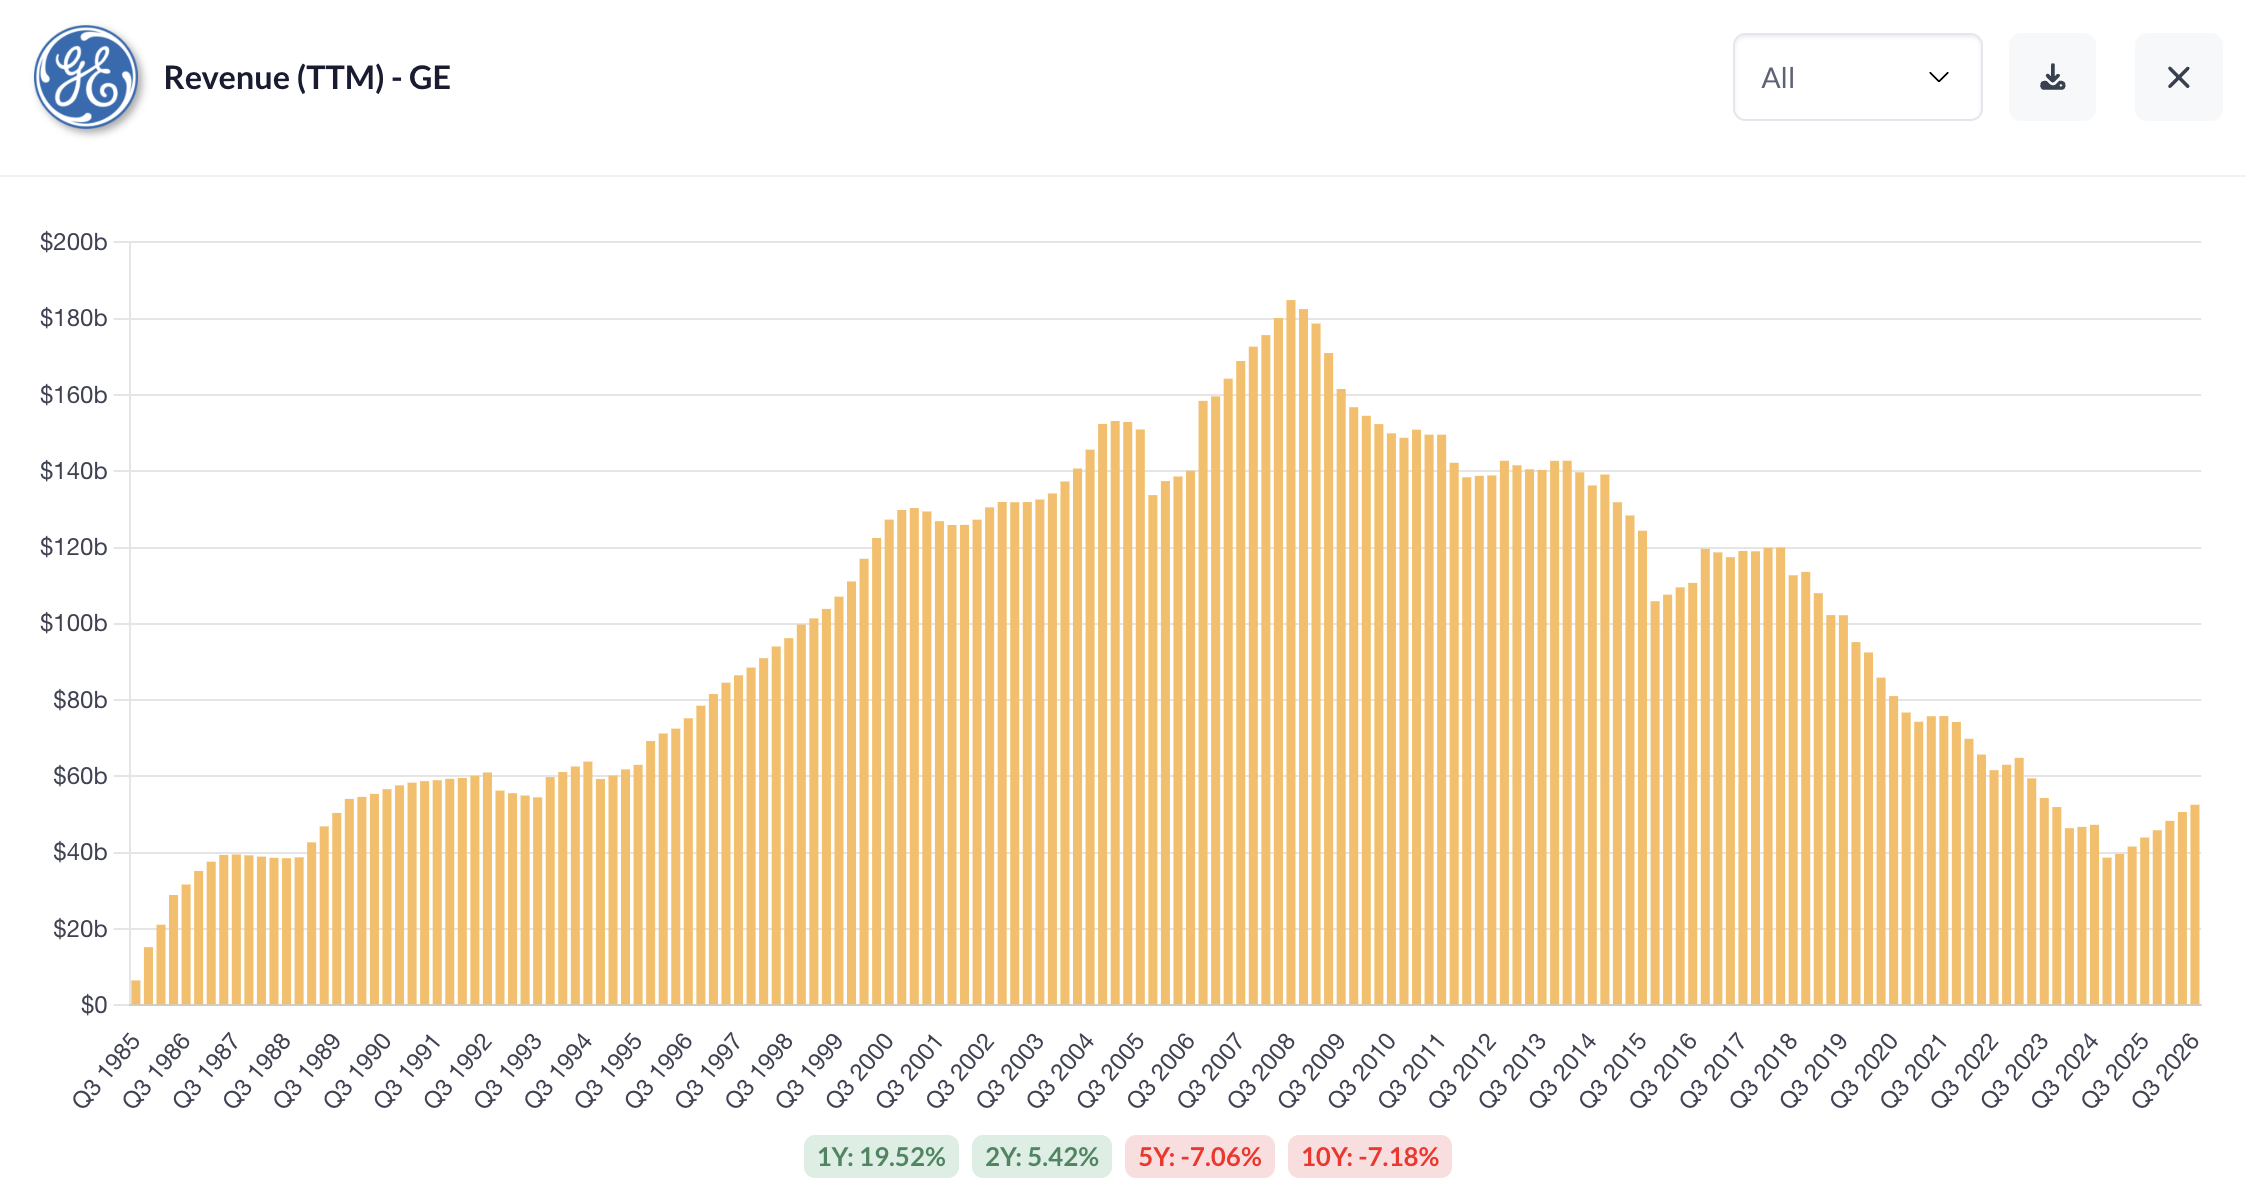
Revenue has been down since their heyday, but it's on an upswing.
Earnings are recovering a bit.
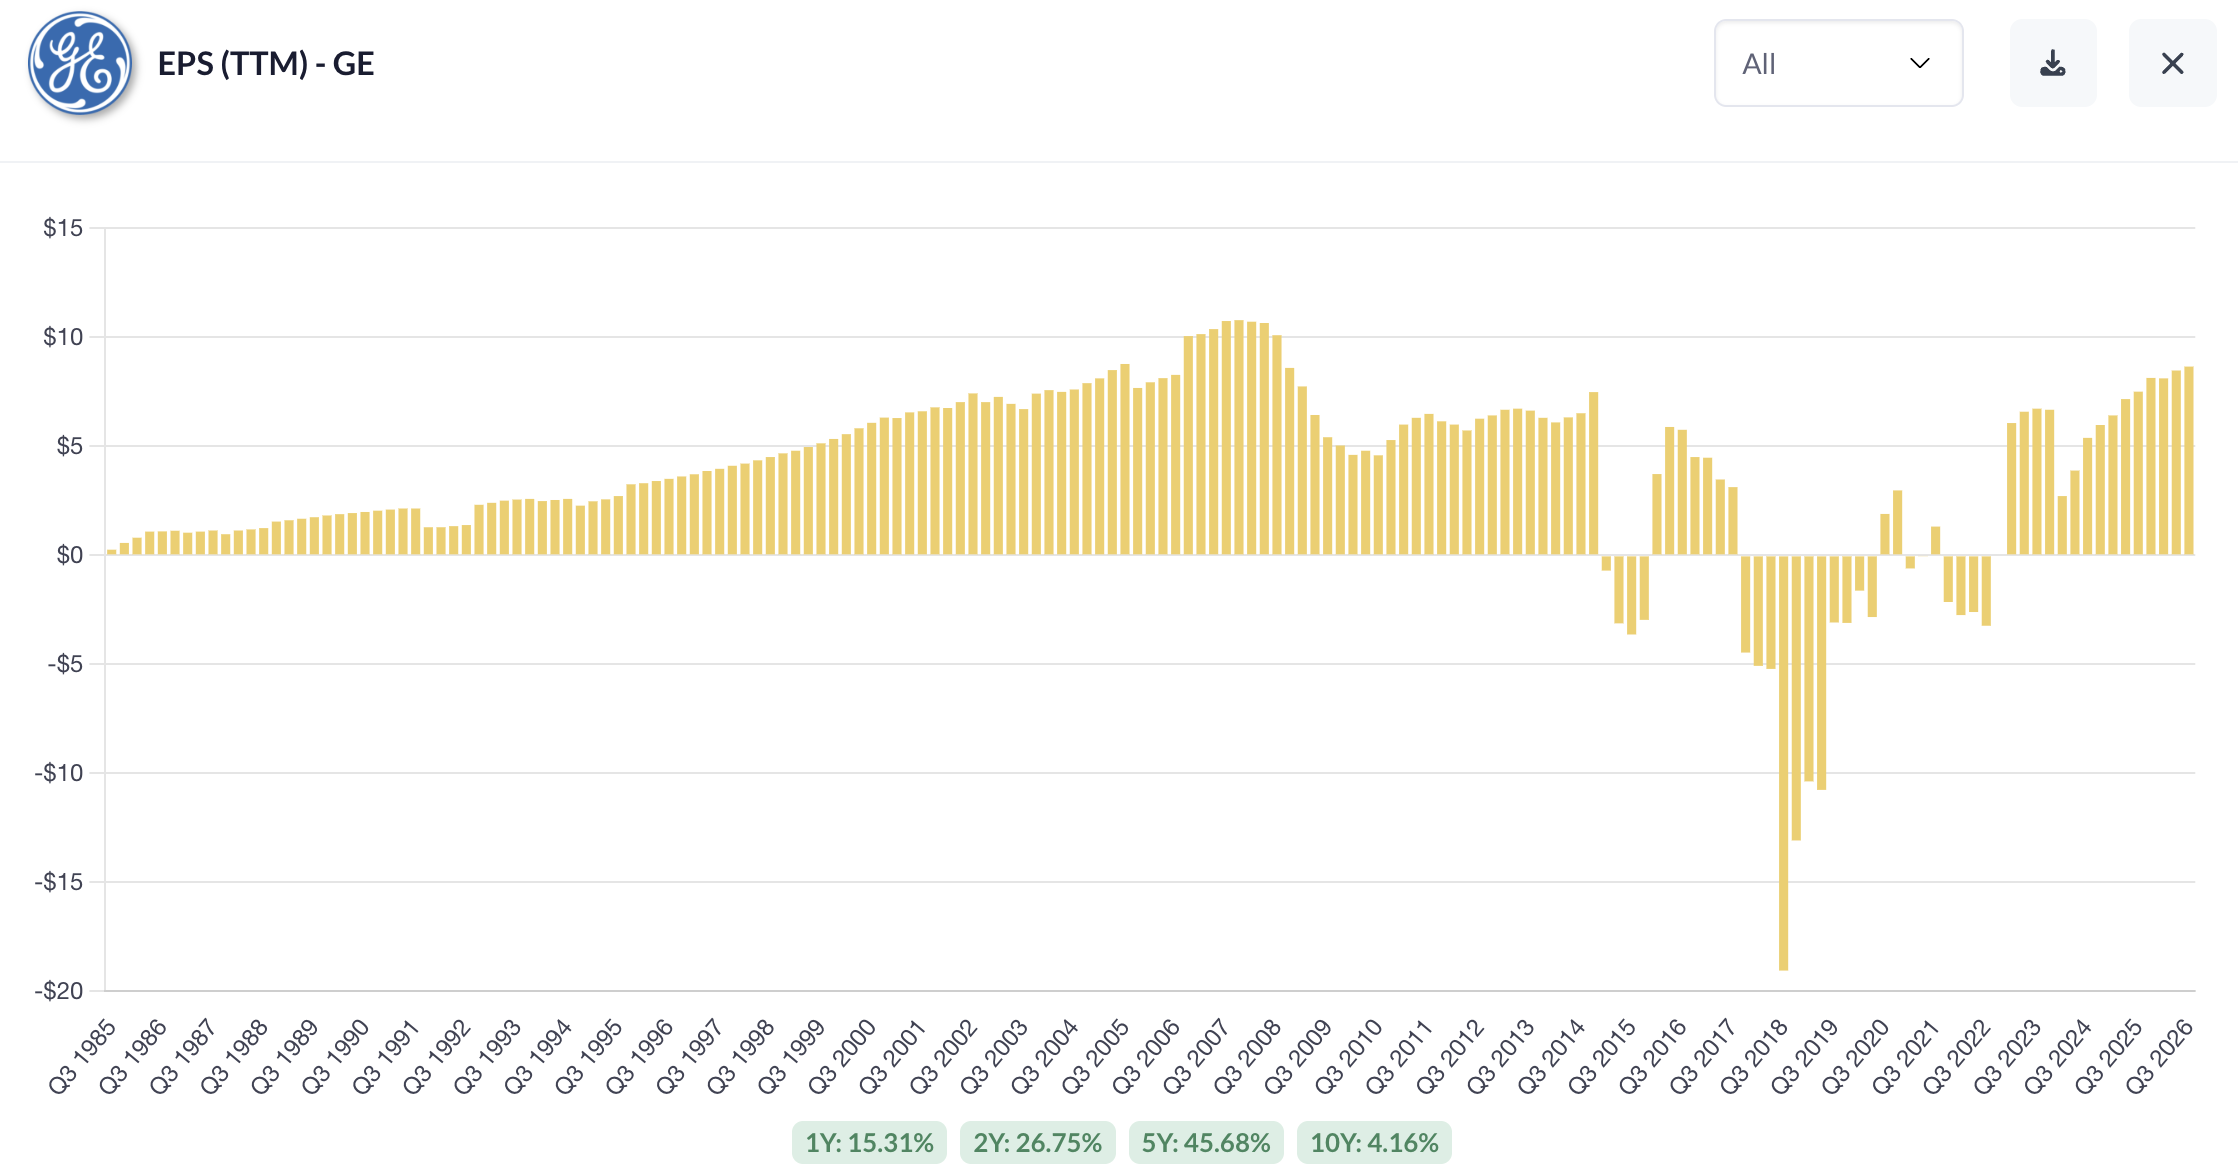
Not the most inspiring charts, but what does Mr. Market think?
Drumroll…
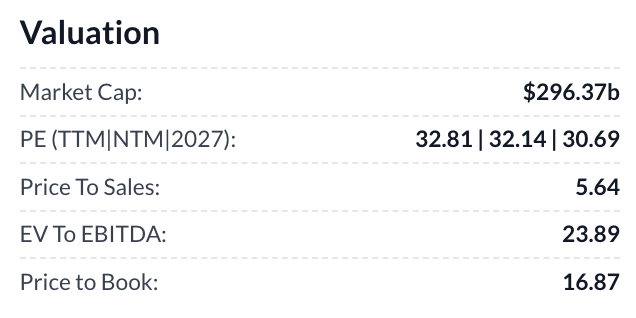
At a 32 FWD PE, GE is at a:
Premium.
Investors love engines, I guess.
SPCX – Space Exploration Technologies Corp.
Elon’s new rocket and satellite internet / super intelligence company. Don’t call it artificial intelligence. It’s super intelligence for all of us north of the Gulf of America and south of Lake America.
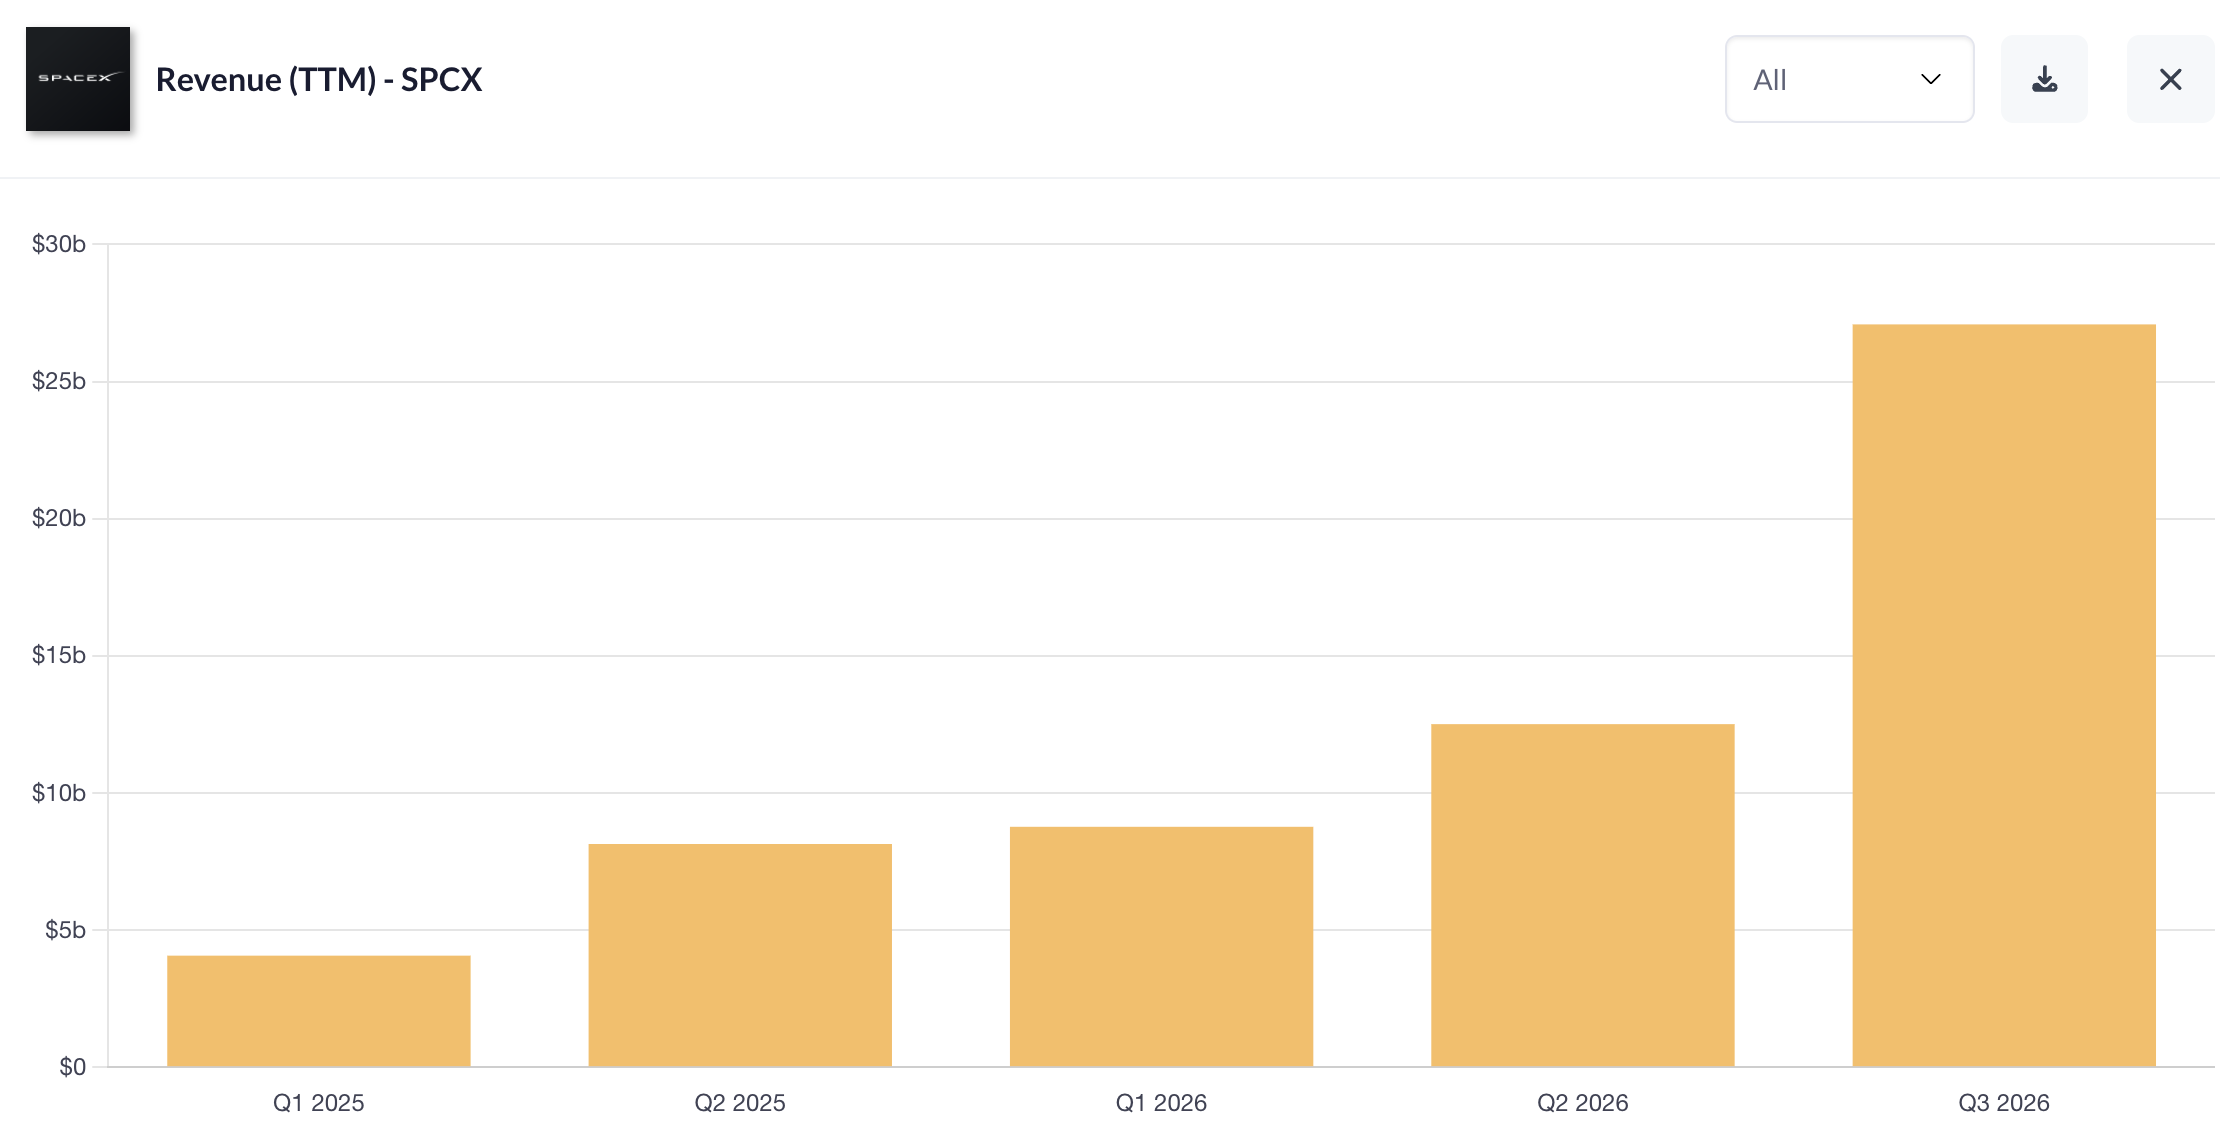
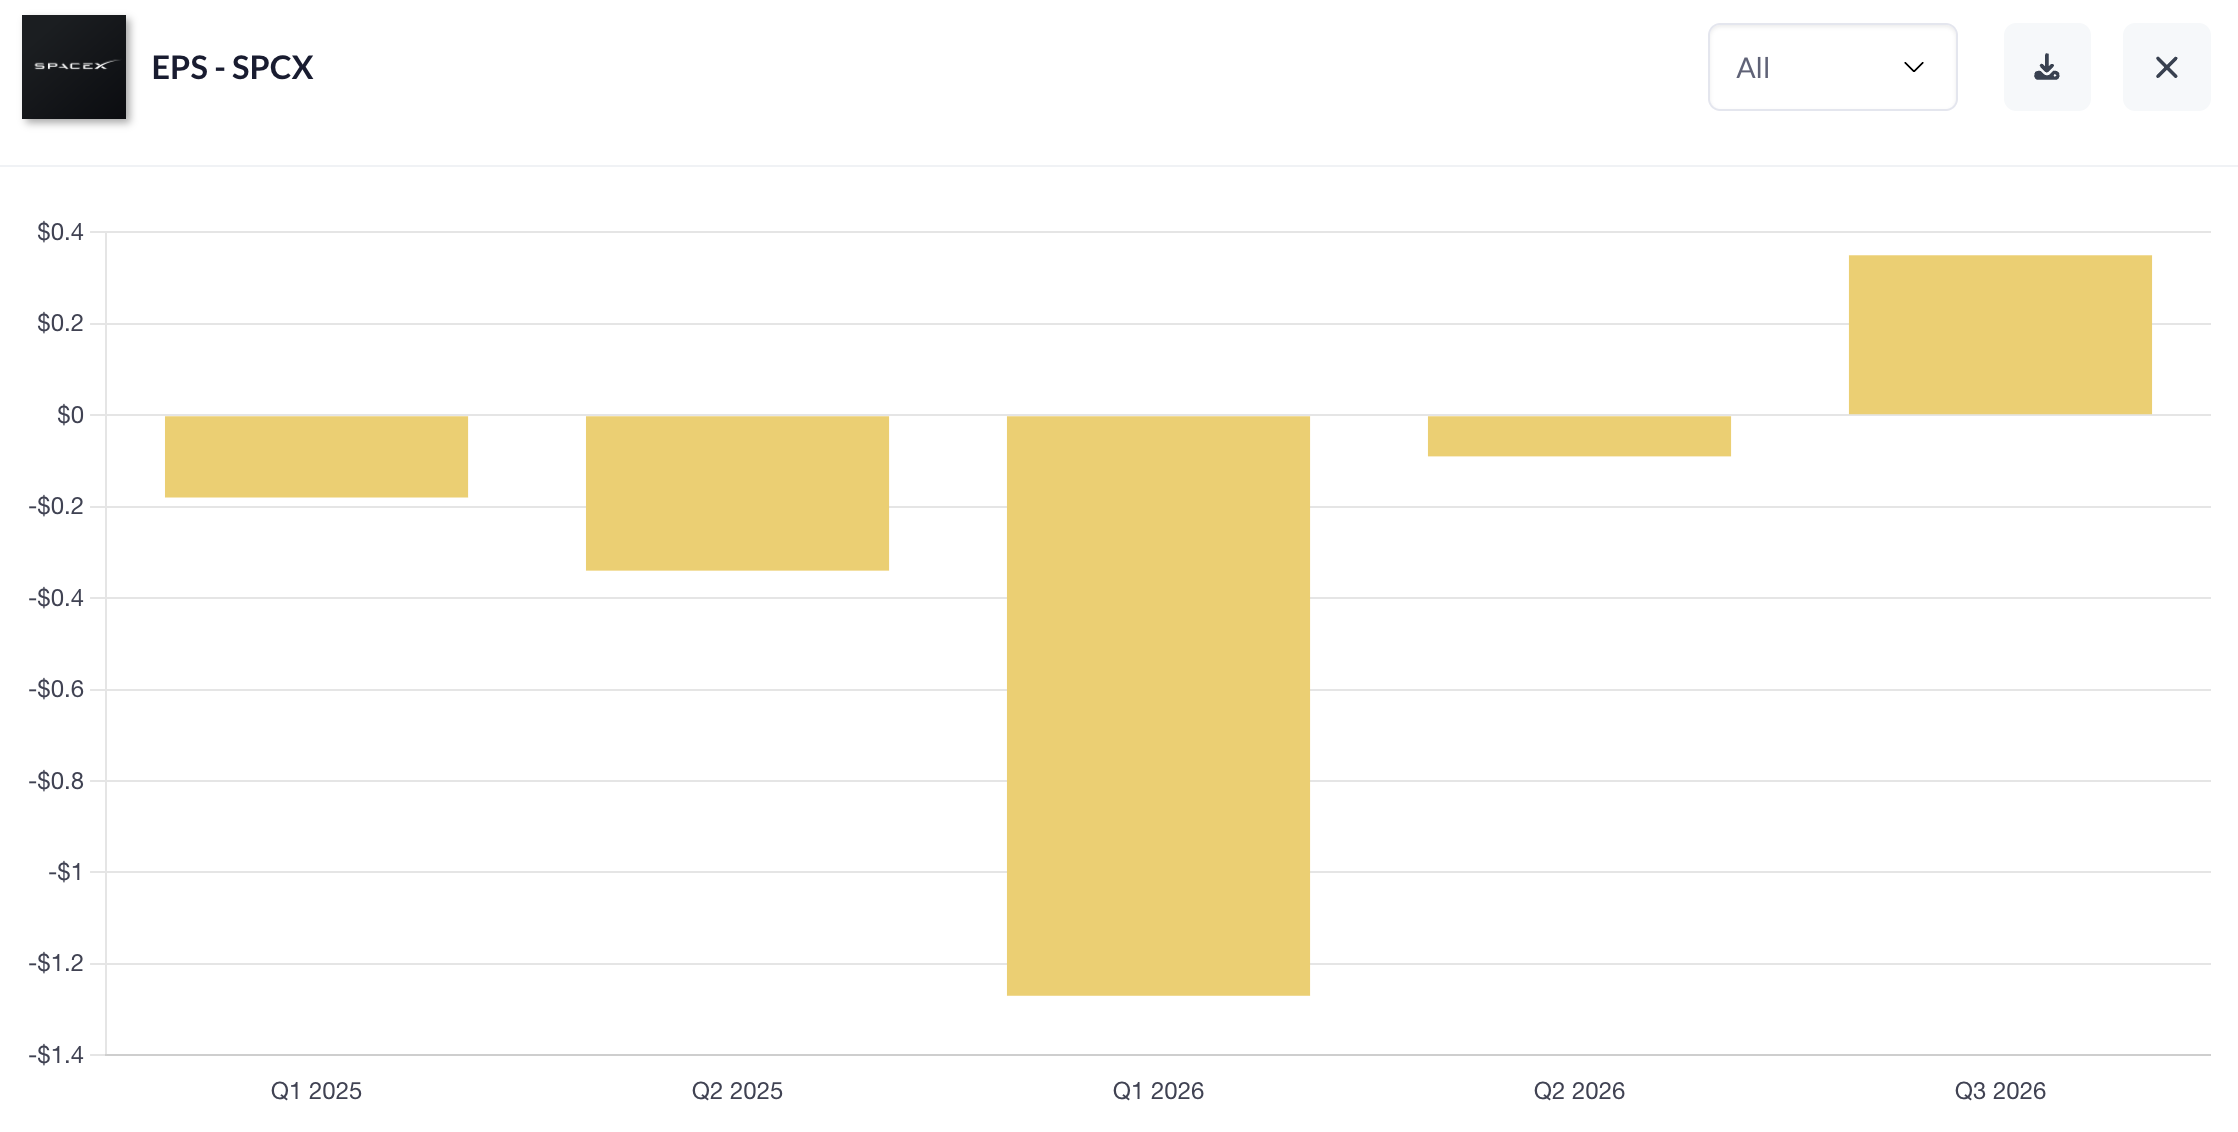
They beat on their quarterly earnings estimates.
Revenue more than doubled in the quarter, which is very impressive.
They also had their first profitable quarter, which is great.
Overall, a very solid start for the company that is currently the seventh most expensive in the world.
But what does Mr. Market think?
Drumroll…
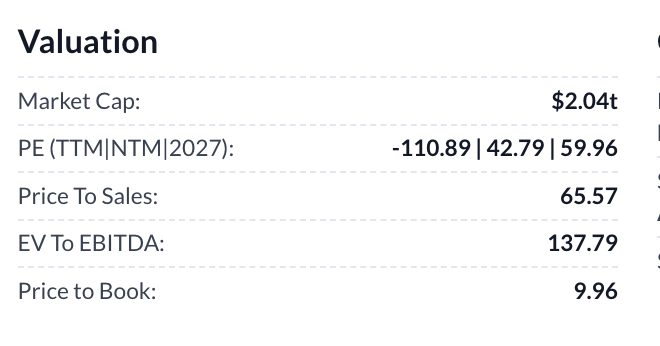
At a 43 FWD PE, SPCX is at a:
Premium.
Investors love Elon’s big push into cutting-edge infrastructure and are rewarding the heavy capital expenditure in hopes of future returns. At only $15B per quarter vs. a market cap of $2T, investors are willing to pay the high price for expectations of future revenue growth.
META – META Platforms, Inc.
The parent company of Facebook, Instagram, WhatsApp, Threads, and Muse with 3.6 billion daily active people. Founded by noted Guinness beer drinker and two-time movie star, Mark Zuckerberg.
They missed on their quarterly earnings estimates due to a little lawsuit costing them about $18B.
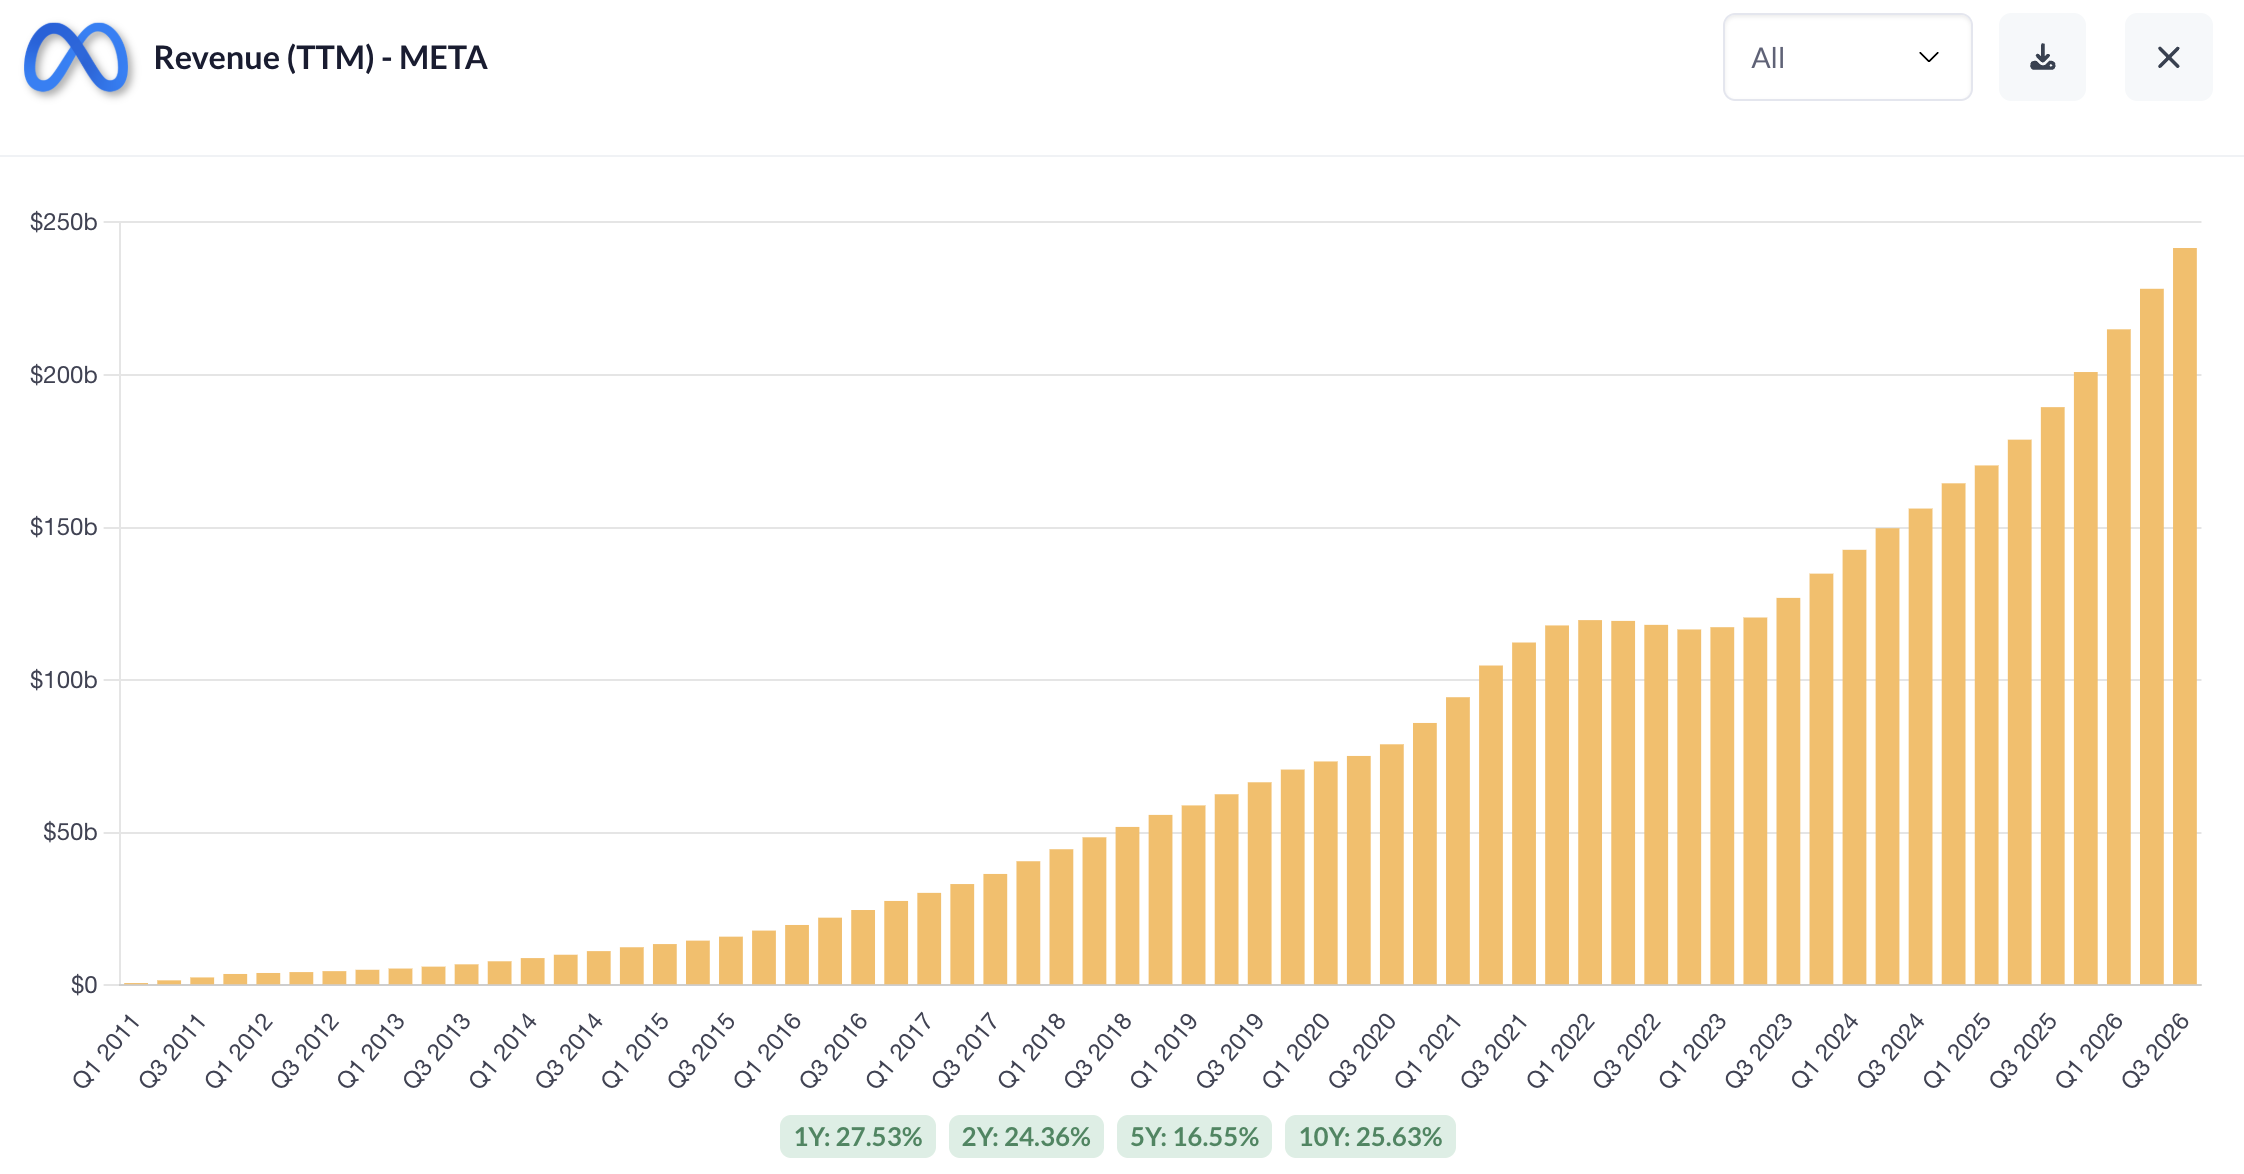
Revenue is growing rapidly, which is very impressive at their size.
Earnings are growing rapidly.
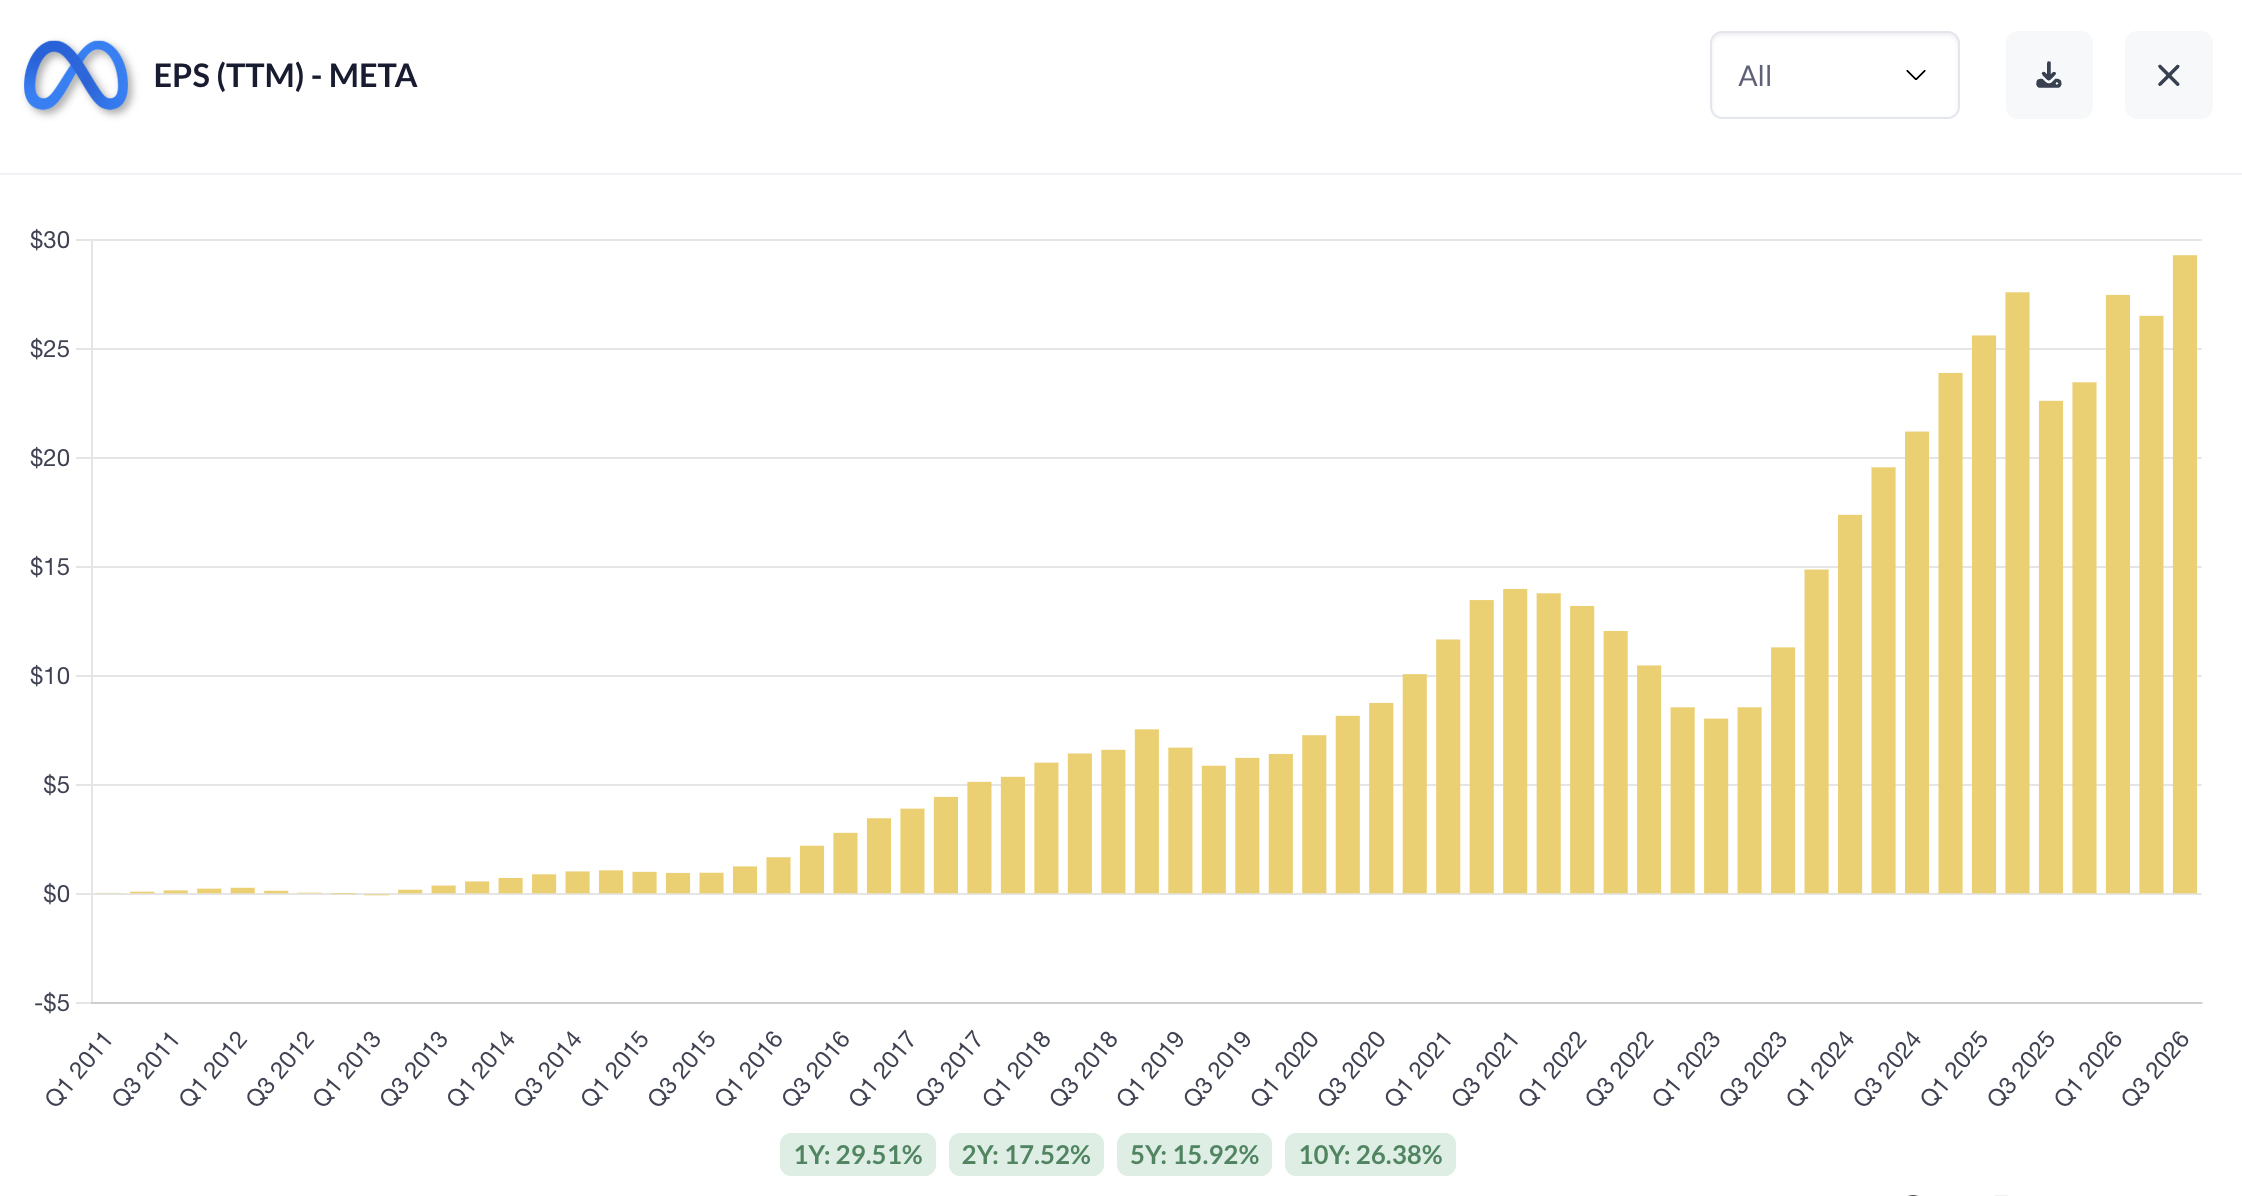
Looks like another solid quarter. Those charts look pretty good. Future estimates look great. Not seeing any holes in the fundamentals.
But what does Mr. Market think?
Drumroll…
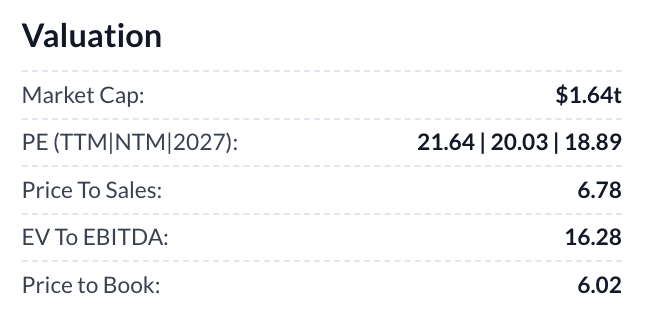
At a 20 FWD PE, META is at a:
Discount.
Investors hate Zuck’s big push into cutting-edge infrastructure and are punishing the heavy capital expenditure in hopes of future returns. At $64B per quarter vs. a market cap of $1.6T, investors are not willing to pay the price for current revenue growth of 26%.
TSLA – Tesla, Inc.
Elon’s car company that also swears that one day it is going to sell robots. We’ll take your word for it, Elon.
They missed on their quarterly earnings estimate.
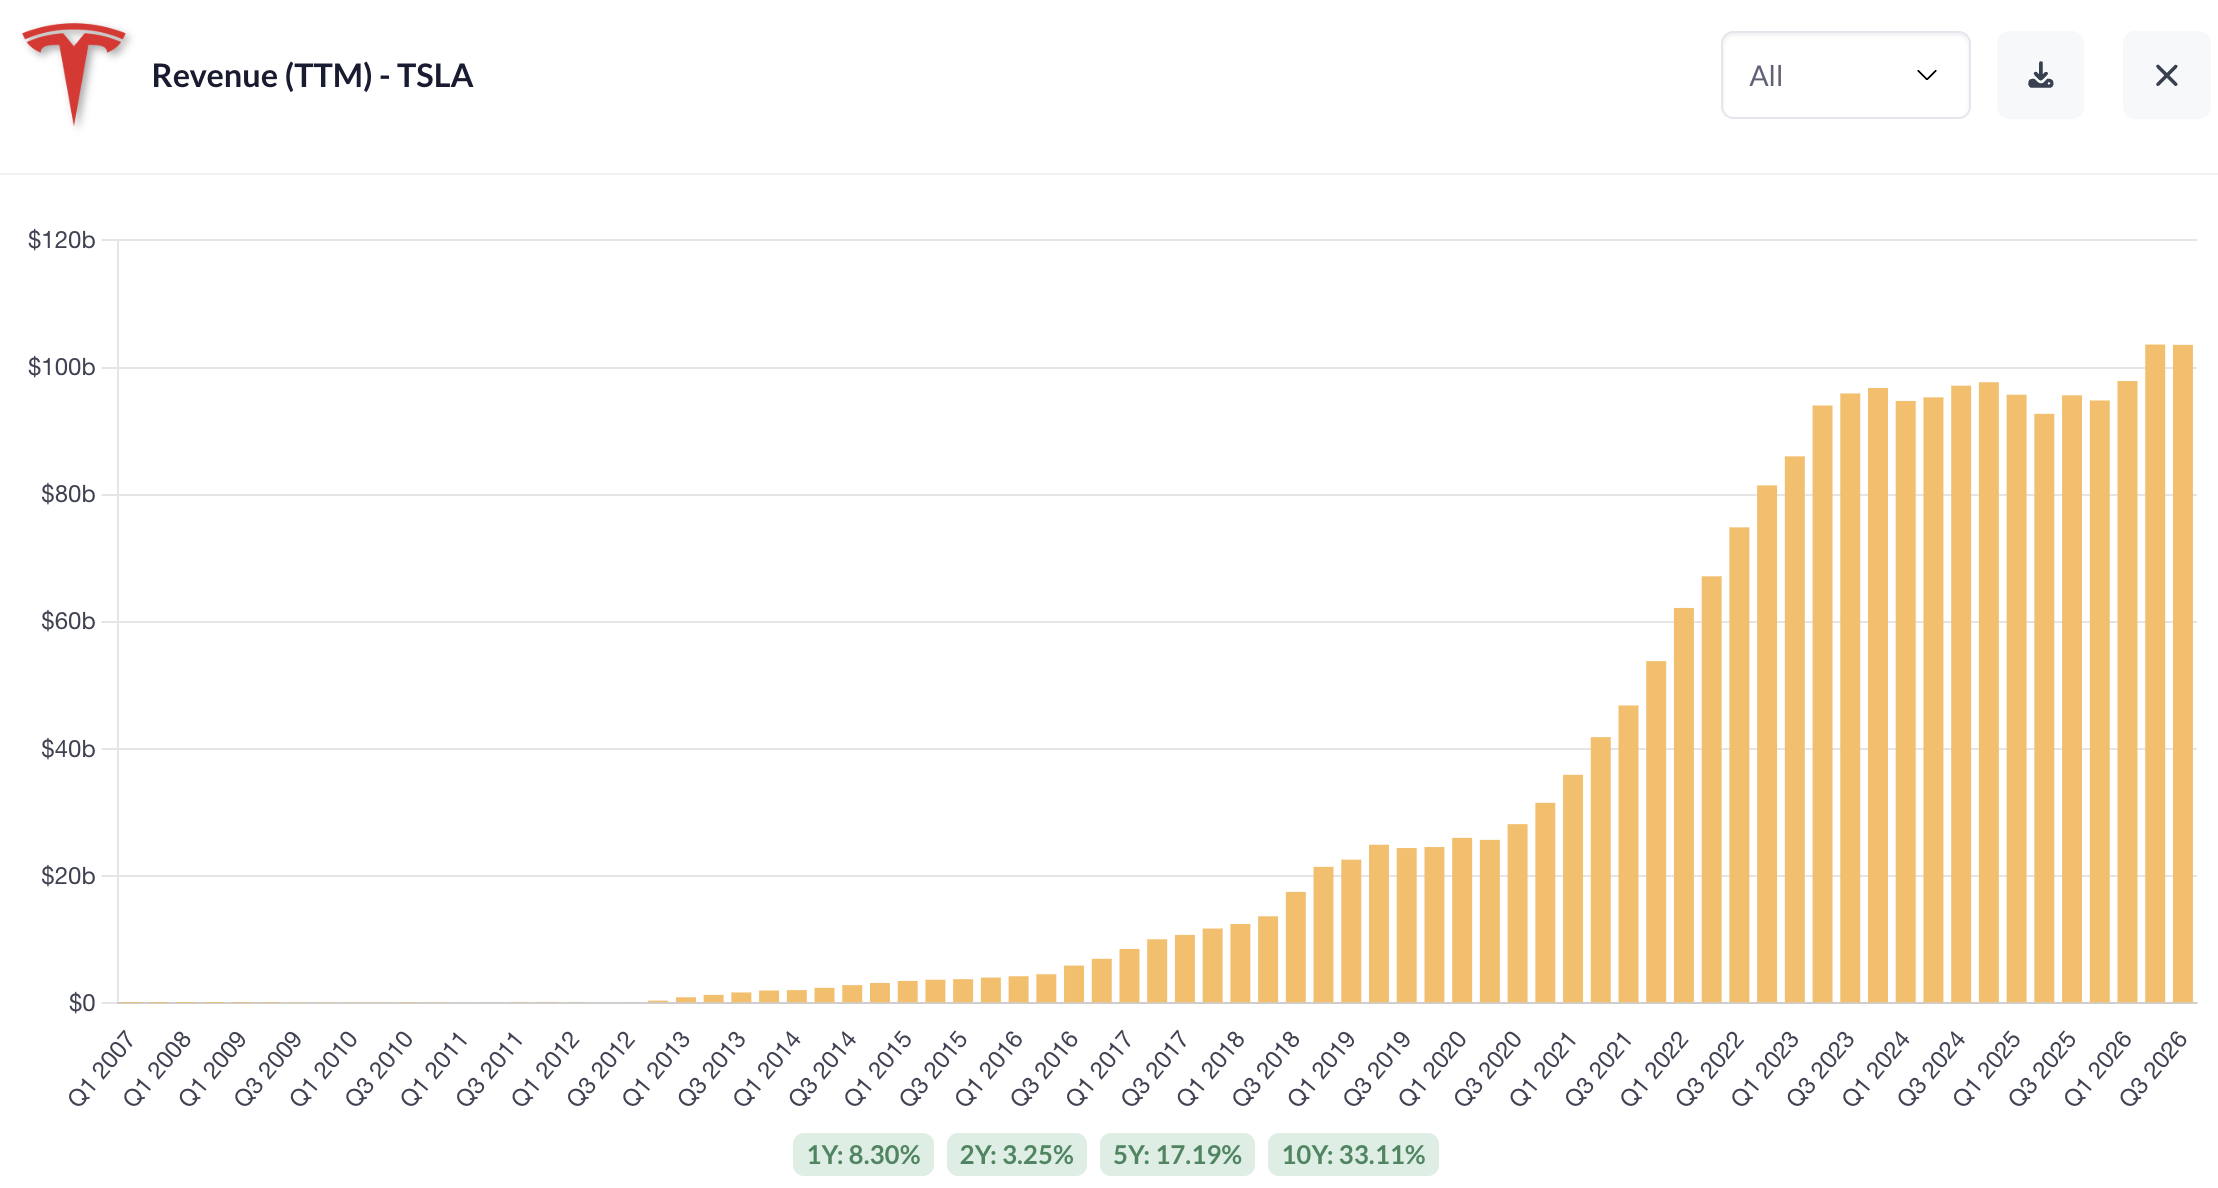
Revenue had a bit of an uptick, although mostly flat the past few years.
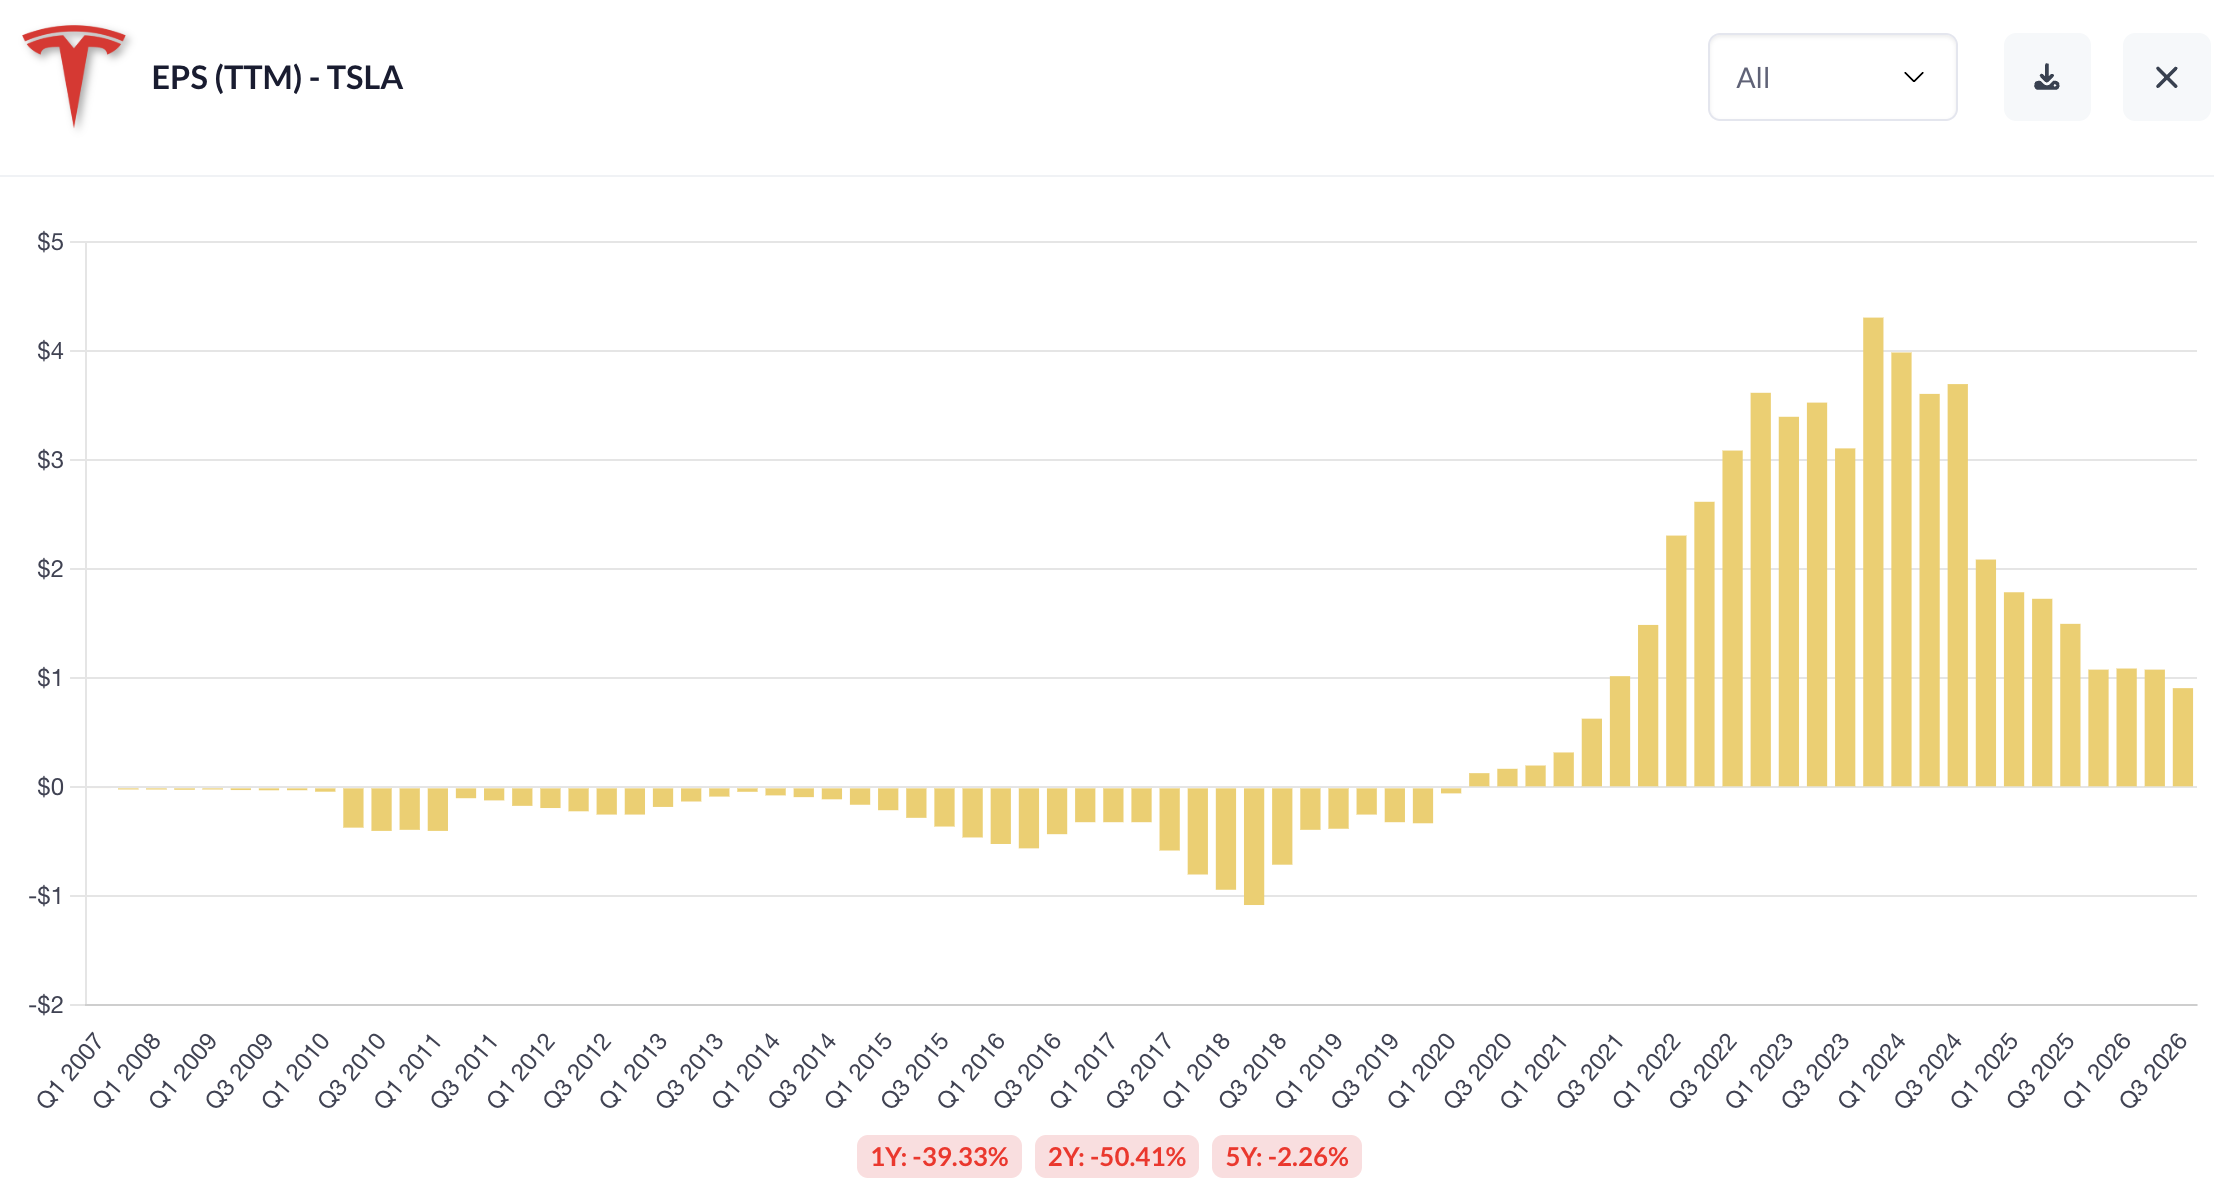
Earnings haven’t looked so great.
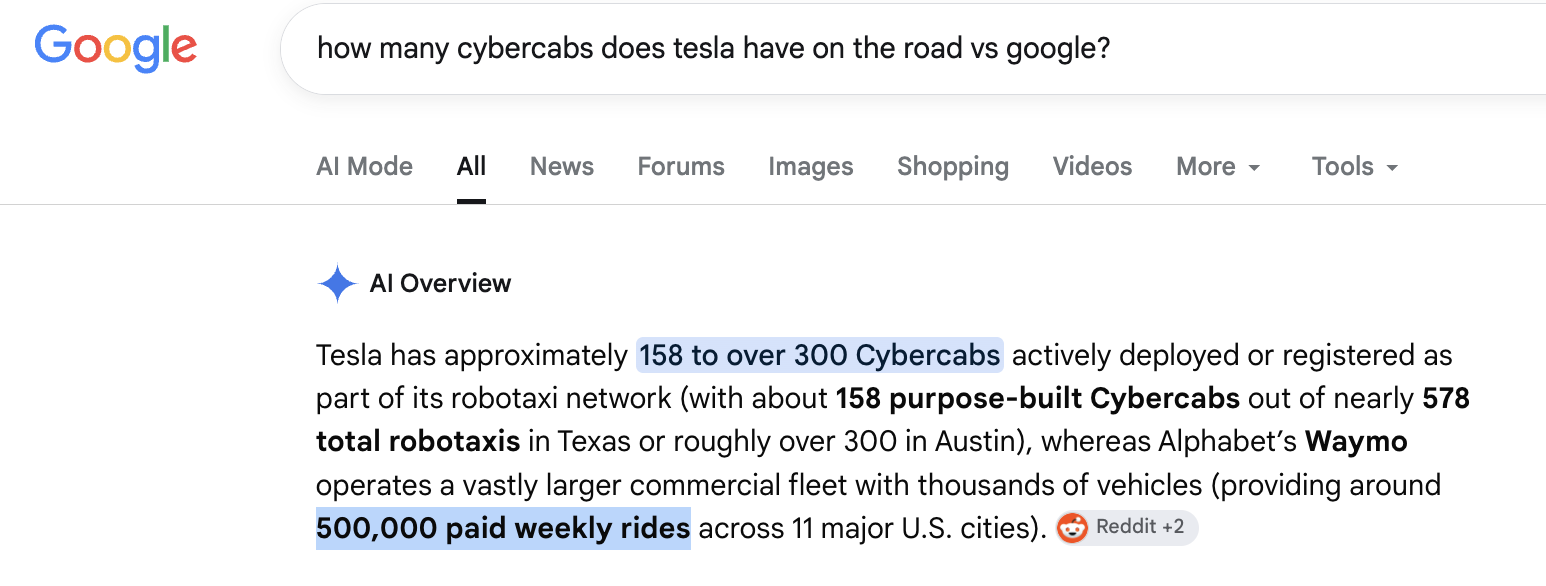
Car sales are flat. Optimus robots are still just a future promise. And after years and years of branding Tesla as the cybercab company, Google has quietly dominated that frontier.
But what does Mr. Market think?
Drumroll…
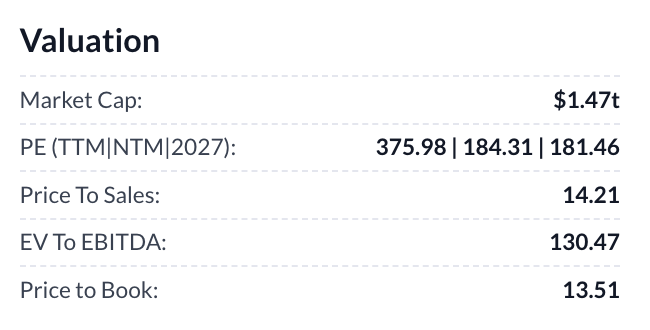
At a 184 FWD PE, TSLA is at a:
Premium.
They just made a rocket car, so fundamentals don’t matter.
NFLX – Netflix, Inc.
Finally, we have the studio that brought you Space Force.
They beat on their quarterly earnings estimates.
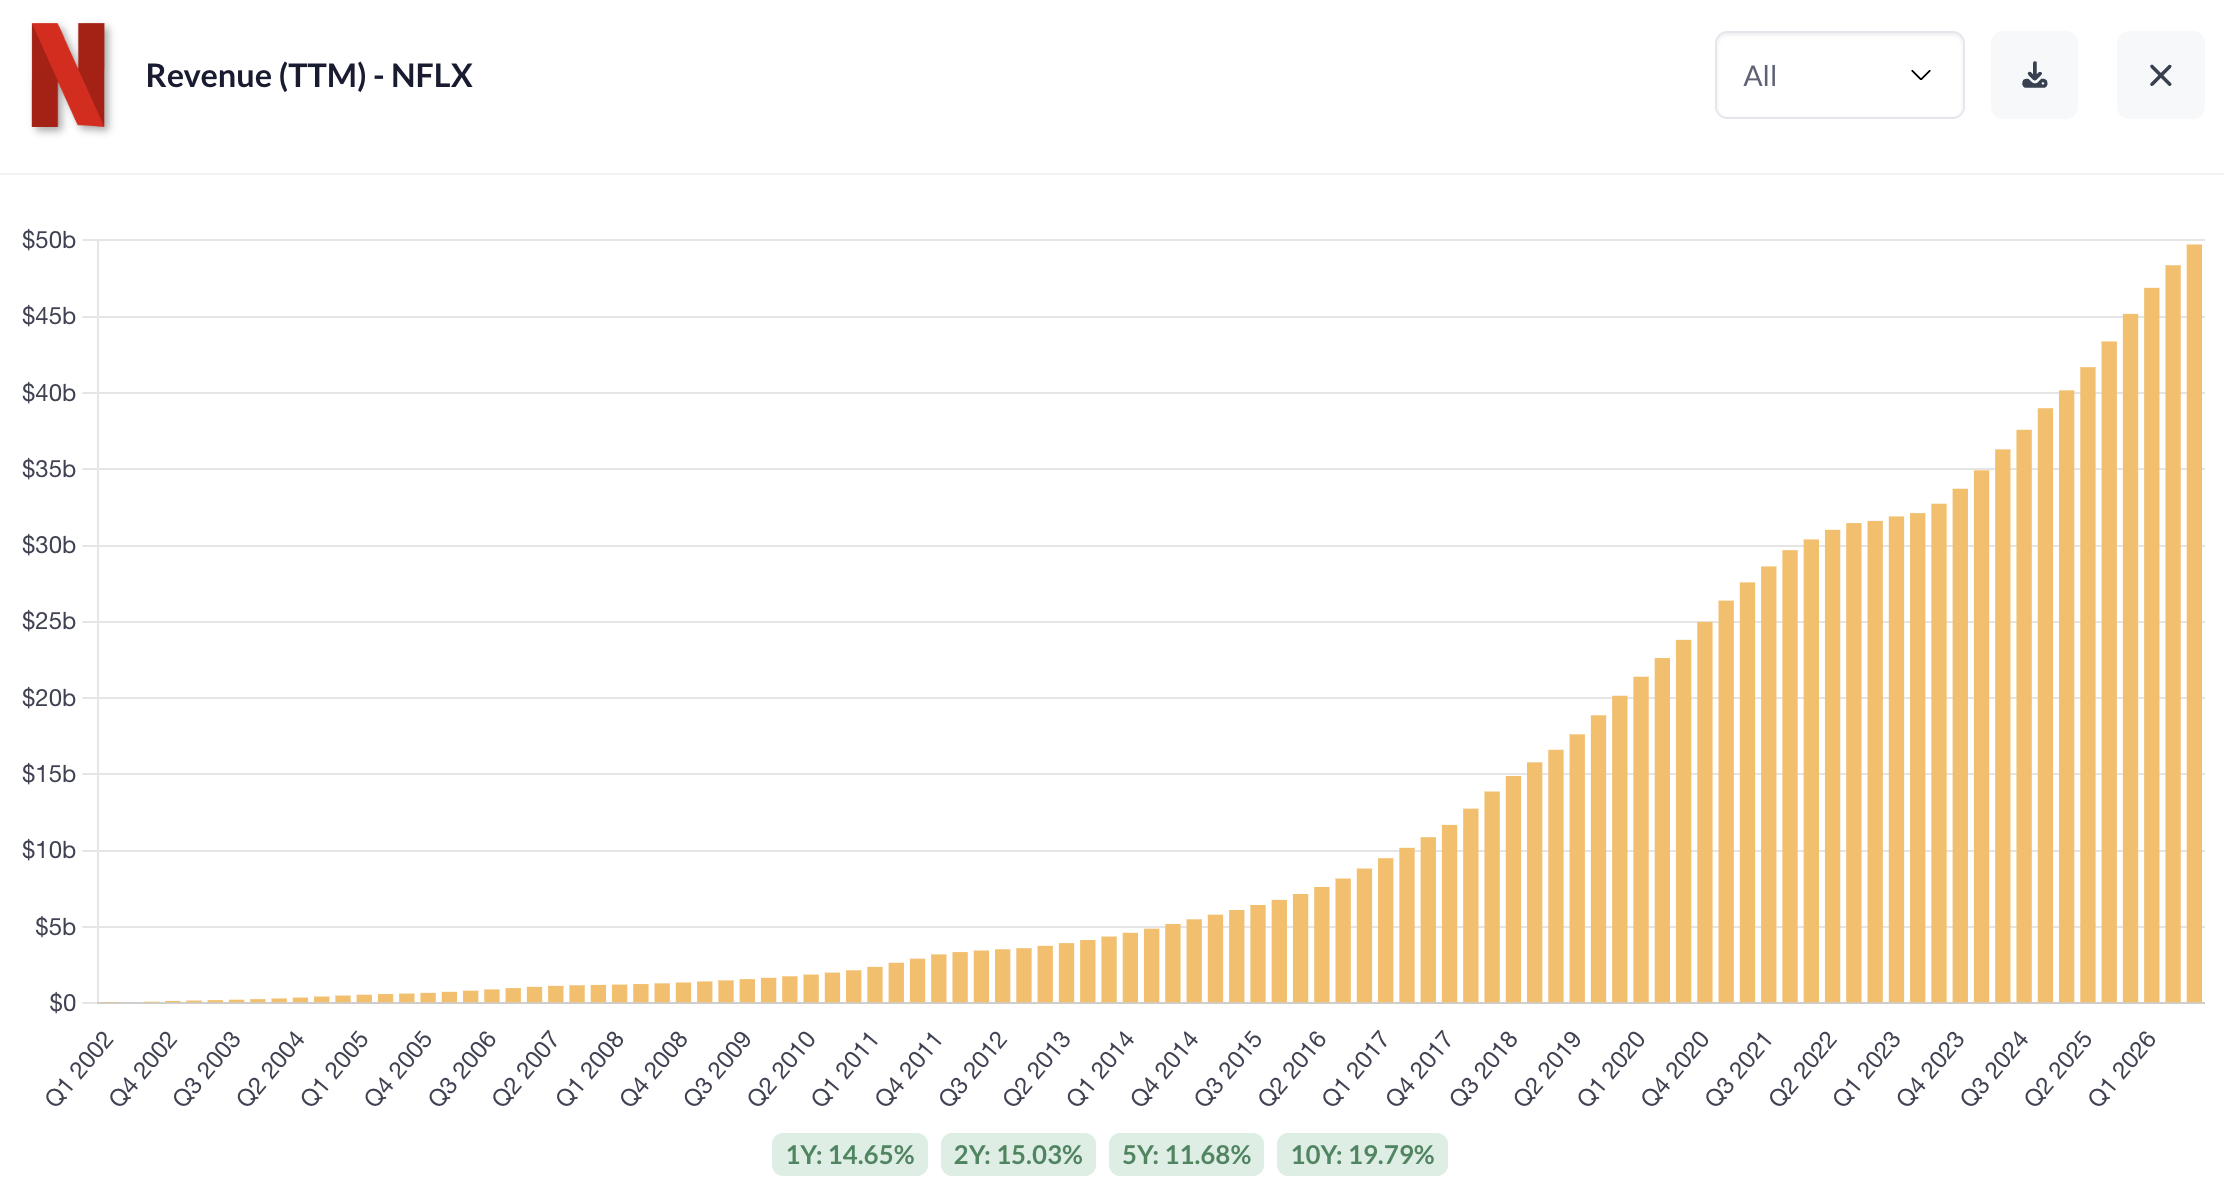
Revenue is growing in the mid-teens.
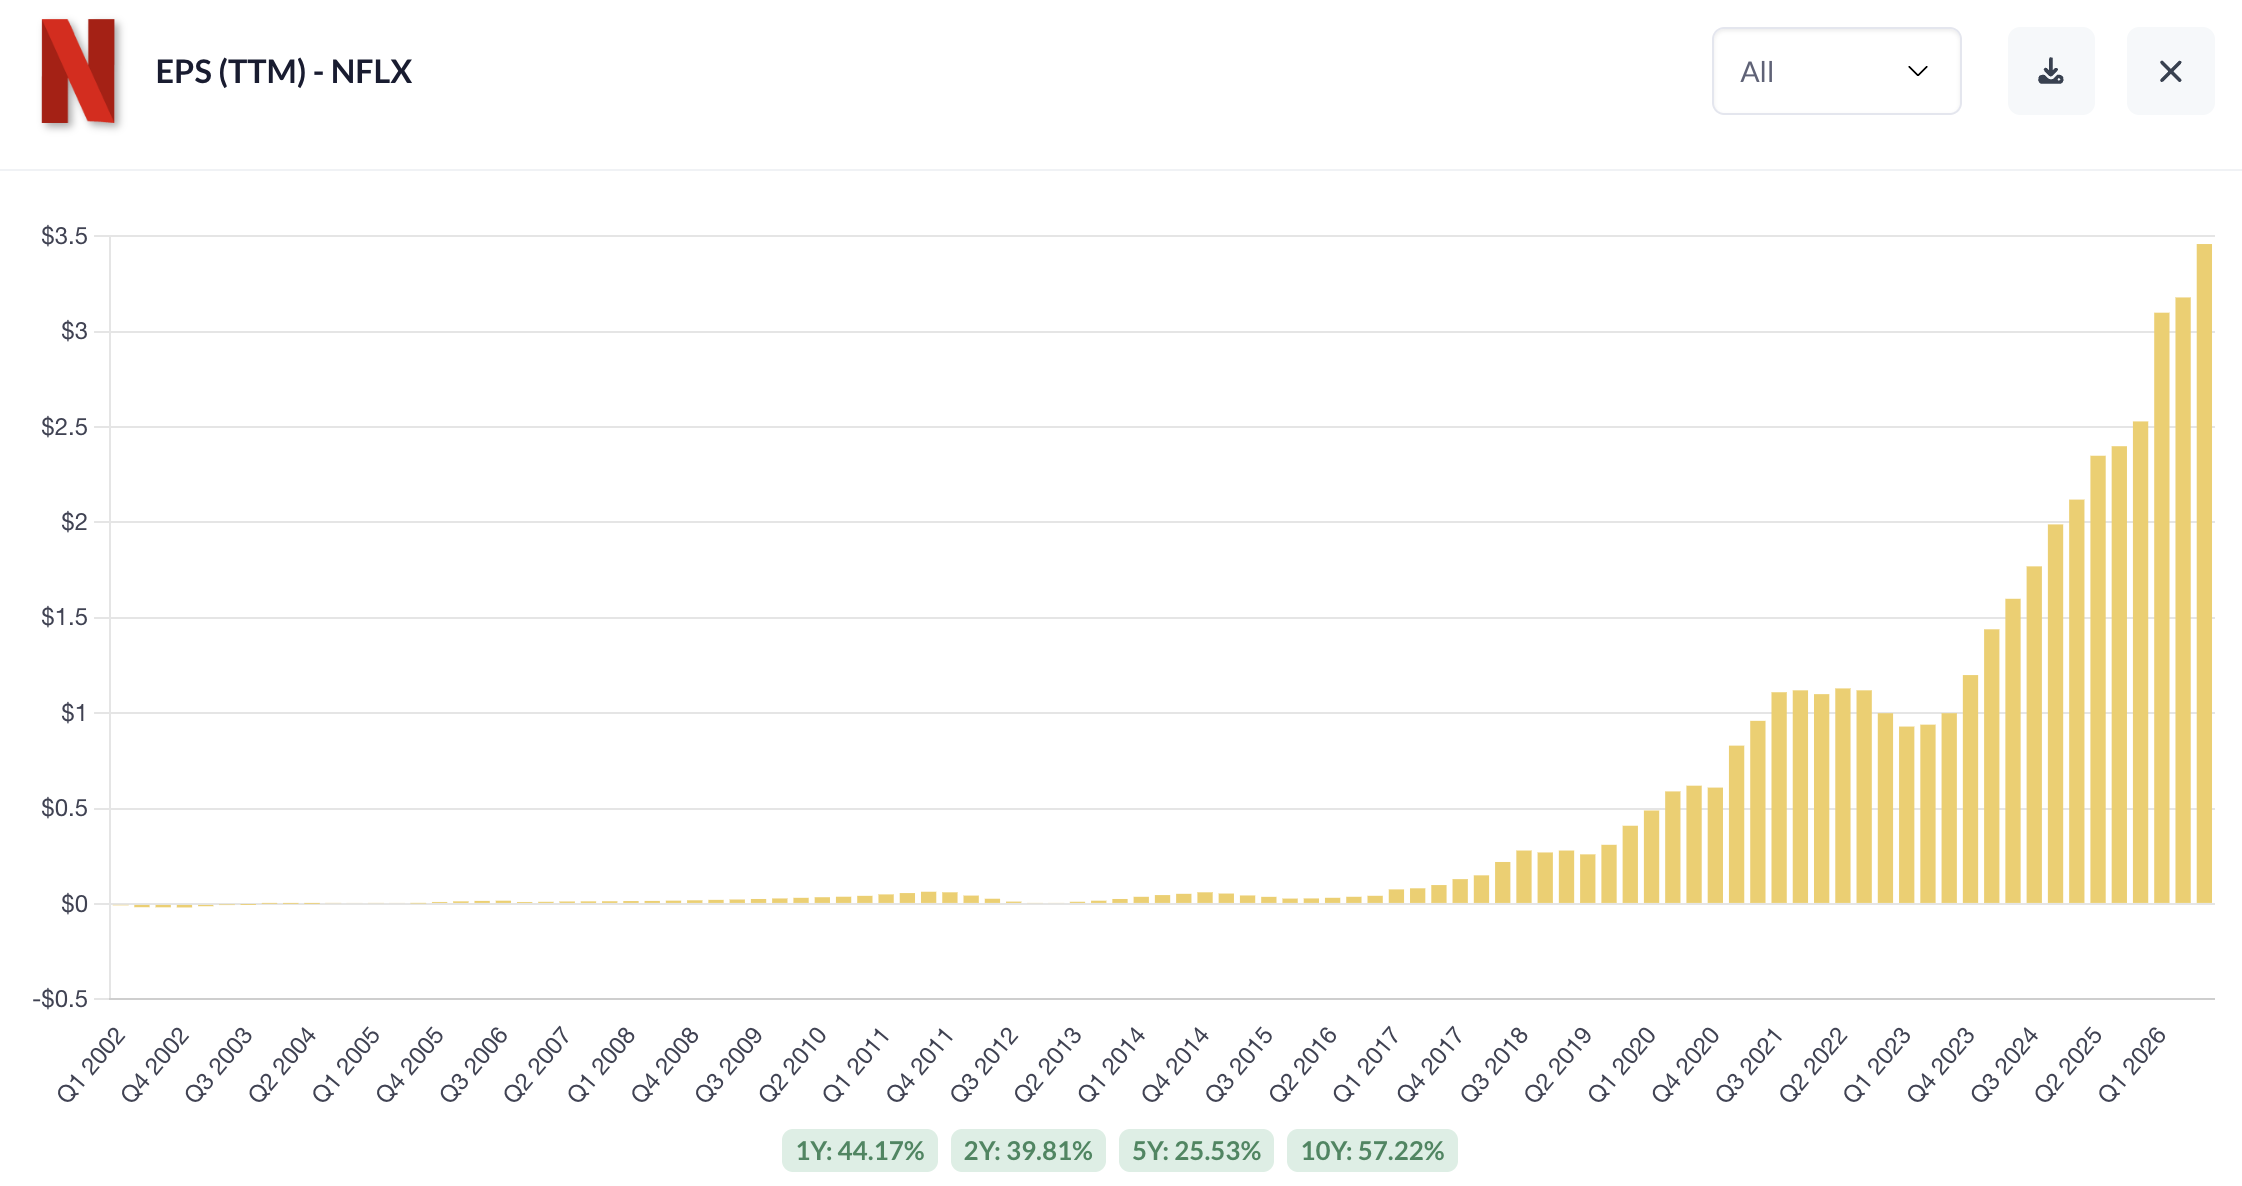
Earnings look awesome.
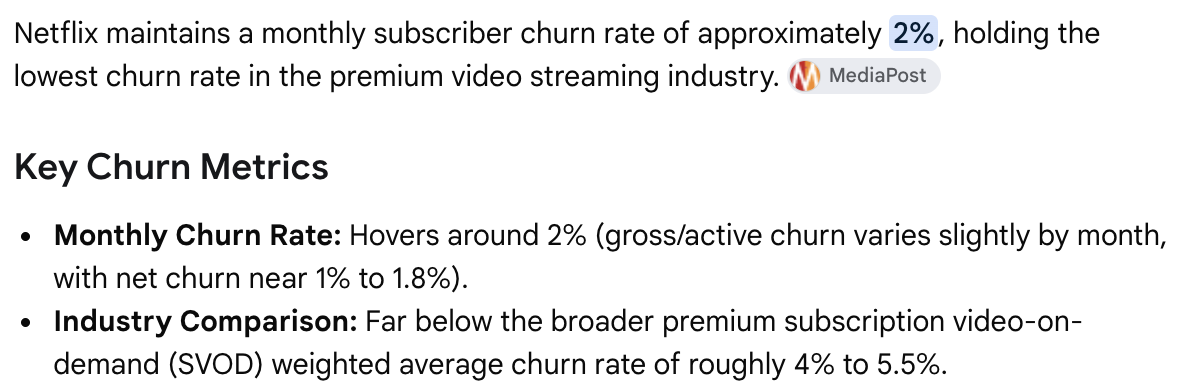
Subscriber count is at an all-time high. They are expanding globally. They have more money than ever to produce content and the lowest cancellation rate of any streaming service.
It looks like smooth sailing for Netflix.
But what does Mr. Market think?
Drumroll…
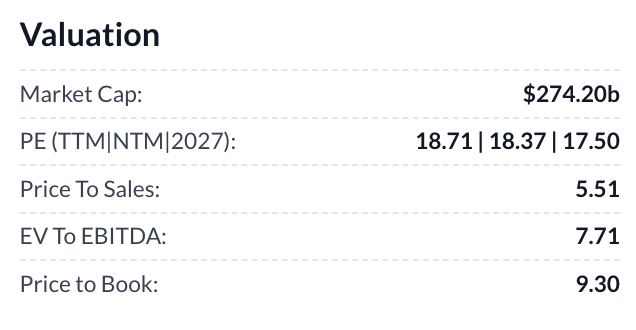
At an 18 FWD PE, NFLX is at a:
Discount.
Haven’t you heard? Netflix is dead. YouTube killed them.
Nobody is watching Netflix because everyone is watching YouTube.
It is simply impossible to watch both. Watch YouTube while maintaining a Netflix subscription? Poppycock!
The real issue is that Netflix hasn’t had an iconic smash in a while. They haven’t had the must-watch hit of K-Pop: Demon Hunters or Stranger Things or Squid Game yet this year.
But spending $5B per quarter on content is a pretty good strategy to hit on something in the future.
Final Thought
“In the short run, the market is a voting machine, but in the long run, it is a weighing machine.” – Benjamin Graham